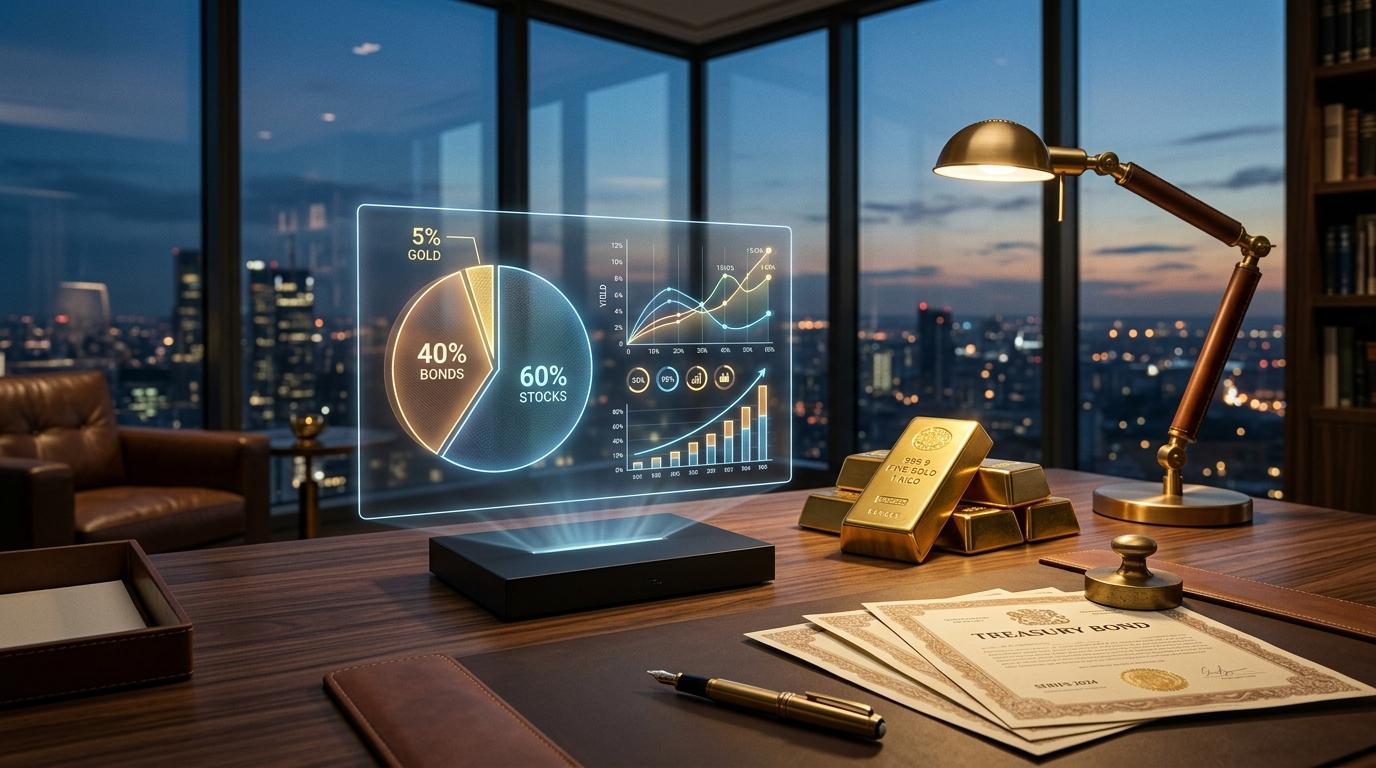
Why Institutional Wealth Managers Are Replacing the 60/40 Portfolio With a 60/20/20 ETF Strategy
For more than four decades, the classic 60/40 portfolio—allocating 60% of capital to equities and 40% to sovereign fixed-income bonds—served as the foundational benchmark for pension funds, family offices, and long-term retail investors. However, persistent sovereign debt expansion, sticky structural inflation, and shifting bond-equity correlations have prompted institutional wealth managers to overhaul traditional asset allocation in favor of a modernized 60/20/20 ETF framework.
Key Takeaways
- Structural Shift Away From Long-Duration Bonds: Rising fiscal deficits across major economies have reduced the hedging effectiveness of long-dated sovereign bonds during inflation shocks.
- The New 60/20/20 Allocation Blueprint: Institutional allocators are retaining a 60% core in high-cash-flow equity ETFs (
$SPY,$QQQ), trimming fixed income to 20% in short-duration Treasury bills, and dedicating 20% to real-asset and digital-asset inflation hedges (Spot Gold and Spot$BTCETFs). - Record Passive ETF Inflows: Low-cost index and thematic Exchange-Traded Funds continue to capture massive capital rotation away from high-fee active mutual funds.
- Superior Sharpe Ratio Profile: Backtested multi-asset portfolios incorporating quality technology compounders, physical gold, and regulated digital asset ETPs have demonstrated stronger risk-adjusted returns.
Why the Traditional 40% Bond Sleeve Is Under Pressure
Historically, institutional portfolio managers relied on 10-year and 30-year government bonds to act as a shock absorber whenever equity markets experienced drawdowns. That negative correlation broke down when inflation surged above central bank targets, causing both stocks and long-duration bonds to sell off simultaneously.
Today, private wealth desks in Zurich, New York, and London are increasingly concentrating their fixed-income exposure at the short end of the yield curve—capturing 4% to 5% risk-free yields in short-term Treasury ETFs without taking excessive duration risk.
Building the 20% Hard-Asset & Alternative Sleeve
By freeing up 20% of the portfolio previously locked in low-yielding long-term bonds, institutional allocators are deploying capital into scarce, non-sovereign store-of-value assets:
- Physical Gold & Commodity ETFs (10%–12%): Sovereign central bank accumulation and geopolitical hedging have turned gold into a core portfolio ballast with low equity correlation.
- Regulated Spot Digital Asset ETPs (3%–5%): With regulated spot
$BTCand$ETHETFs now accessible on major brokerage platforms, wealth managers are sizing a disciplined 3% to 5% allocation to capture asymmetric monetary growth. - Infrastructure & Cash-Flow REITs (3%–5%): Data center infrastructure and energy transmission assets provide inflation-linked dividend streams tied to the global AI buildout.
Core Equity Positioning: Quality Compounders Over Broad Beta
Within the 60% equity allocation, institutional strategists emphasize balance-sheet fortress companies with high free-cash-flow margins and durable pricing power. Blending broad S&P 500 exposure ($SPY) and Nasdaq-100 innovation leaders ($QQQ, $NVDA) with dividend-growth aristocrats ensures participation in secular technology growth while buffering downside volatility.
Frequently Asked Questions (FAQ)
What is the 60/20/20 portfolio strategy?
The 60/20/20 strategy allocates 60% of a portfolio to diversified global equities, 20% to short-duration fixed income and cash equivalents, and 20% to inflation-resistant hard assets such as gold, commodities, infrastructure, and regulated spot $BTC ETFs.
How often should long-term investors rebalance ETF portfolios?
Institutional portfolio managers typically rebalance either semi-annually or whenever an asset class drifts more than 5 percentage points from its target weight, systematically trimming outperformers and adding to undervalued sleeves.