

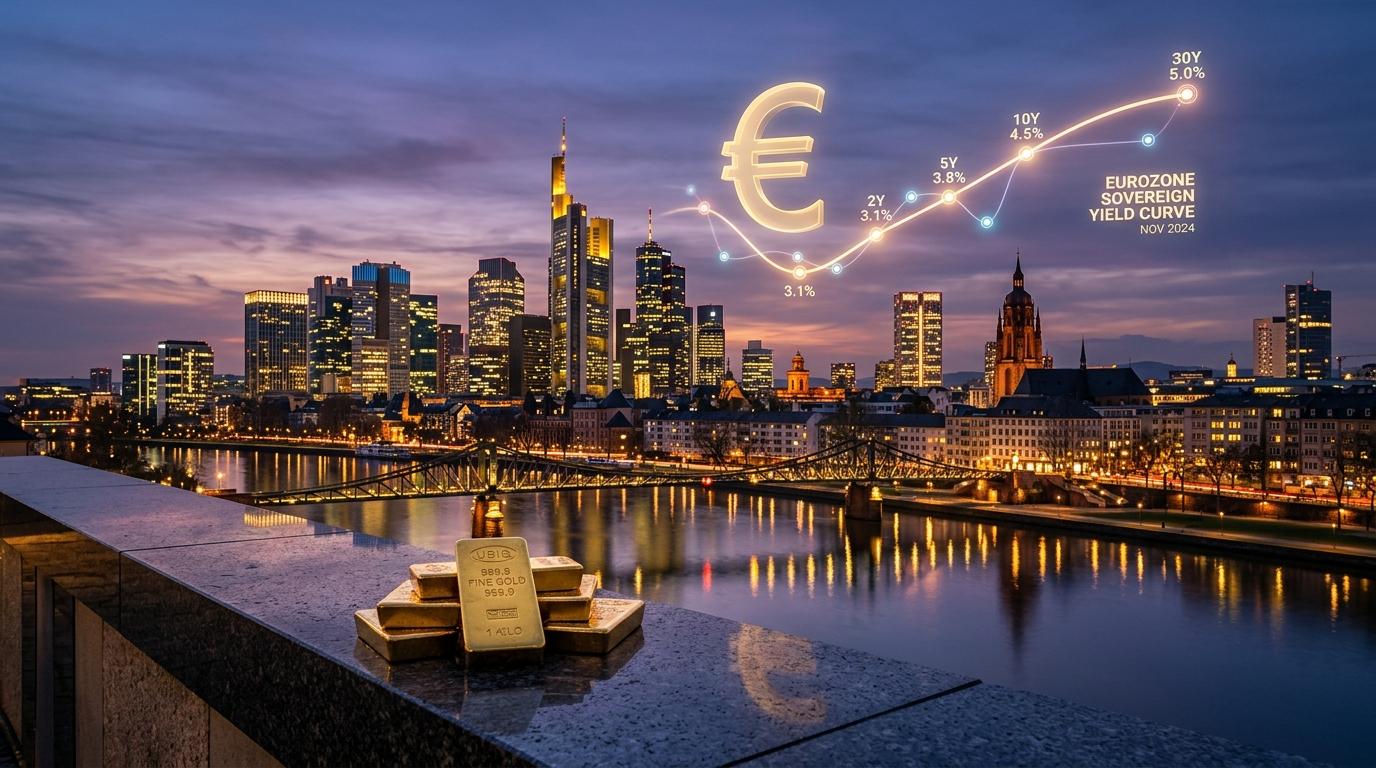
European Sovereign Yields Retreat as Credit Ratings Hold: What OAT-Bund Spreads Mean for EUR/USD and Gold (XAU/USD)
European fixed-income and foreign exchange markets opened the week with a notable relief rally as French sovereign bond yields pulled back from multi-year highs following a steady credit rating decision. The narrowing of the closely watched Franco-German 10-year yield spread (OAT-Bund) has alleviated immediate tail-risk pressure on the Euro (EUR/USD), shifting institutional macro focus back toward upcoming European Central Bank (ECB) monetary policy guidance and global safe-haven demand in XAU/USD (Spot Gold) and USD/JPY.
Key Takeaways
- Sovereign Spread Compression: French 10-year OAT yields retreated from cycle highs after sovereign rating stability calmed institutional fears of forced bond-index selling.
- EUR/USD Finds Near-Term Floor: Reduced European fiscal contagion risk has helped stabilize EUR/USD above critical technical support zones ahead of ECB commentary.
- ECB Rate Cut Trajectory in Focus: With Eurozone headline inflation moderating and manufacturing PMIs remaining soft, FX swaps price in continued policy easing by the ECB.
- Gold (XAU/USD) Retains Fiscal Hedge Bid: Despite short-term European bond relief, elevated sovereign debt-to-GDP ratios across G7 economies continue to underpin structural central bank and institutional allocation into XAU/USD.
Why French OAT Yields and Sovereign Spreads Matter for FX Traders
In global macro trading, sovereign bond spreads within the Eurozone serve as a real-time barometer of regional financial fragmentation risk. When the yield premium investors demand to hold French government debt (OATs) over German Bunds widens sharply, institutional FX desks typically hedge by reducing Euro exposure and rotating into traditional safe havens such as the U.S. Dollar, the Swiss Franc (EUR/CHF), and Spot Gold (XAU/USD).
By avoiding an immediate sovereign downgrade into a lower rating tier, French debt avoided mechanical selling pressure from mandate-constrained institutional bond funds and Asian sovereign reserve managers. Consequently, 10-year yields retreated from their highest levels since 2002, prompting short-covering across European bank equities and stabilizing the single currency.
Fiscal Deficits Remain a Medium-Term Macro Headwind
While the immediate rating decision provided tactical relief, macro strategists emphasize that underlying fiscal consolidation challenges remain unresolved. France and several other G7 economies face elevated interest servicing costs as legacy low-coupon debt rolls over at higher market rates, keeping sovereign bond vigilantes alert to parliamentary budget negotiations.
ECB Monetary Policy and the EUR/USD Rate Differential
With acute sovereign spread pressure easing for now, currency traders are refocusing on relative central bank interest rate differentials between the ECB and the Federal Reserve. If Eurozone growth indicators remain sluggish while U.S. economic data demonstrates resilience, the two-year swap rate differential will continue to dictate directional trend momentum in EUR/USD.
Safe-Haven Flows into Gold (XAU/USD) and USD/JPY
For commodity and cross-currency traders, sovereign debt dynamics in Europe and North America reinforce the long-term investment case for hard monetary assets. Every episode of sovereign bond volatility accelerates institutional portfolio diversification into physical bullion and XAU/USD, while rate-sensitive carry unwinds continue to drive two-way volatility in USD/JPY.
Frequently Asked Questions (FAQ)
How do French government bond yields affect the Euro (EUR/USD)?
Rising French yields relative to German Bunds signal fiscal stress within the Eurozone's second-largest economy, which increases risk premiums on European assets and weighs on EUR/USD. When yields retreat and spreads narrow, the Euro typically stabilizes.
What is the OAT-Bund spread?
The OAT-Bund spread measures the difference in yield between 10-year French government bonds (Obligations Assimilables du Trésor) and 10-year German government bonds (Bunds), acting as the primary gauge of Eurozone sovereign credit risk.
Why does Gold (XAU/USD) benefit from G7 sovereign debt concerns?
Gold carries no sovereign credit risk or fiscal deficit liability. When government debt-to-GDP ratios and bond yields rise across major economies, central banks and institutional funds increase allocations to XAU/USD as a long-term store of value.




