

What Is a Stablecoin? How USDT, USDC and DAI Hold Their $1 Peg — Explained
A stablecoin is a crypto token designed to stay at $1 — and the interesting part is not the target, it is the machinery that defends it
A stablecoin is a cryptocurrency designed to hold a steady value, almost always $1, while the rest of the crypto market swings around it. That stability is what makes stablecoins useful: traders park profits in them without leaving crypto, DeFi protocols price loans in them, and people in countries with volatile local currencies use them as a dollar-like balance on a phone. As of April 2026, stablecoins were roughly a $270–320 billion market, with Tether's USDT at about $189.6 billion and Circle's USDC at about $77.6 billion in circulation, and MakerDAO's DAI at about $4.7 billion. But "stable" describes a goal, not a guarantee. There are three different engineering approaches behind the $1 promise, and each fails in a different way. Understanding which one backs the token you hold is the single most useful stablecoin skill there is.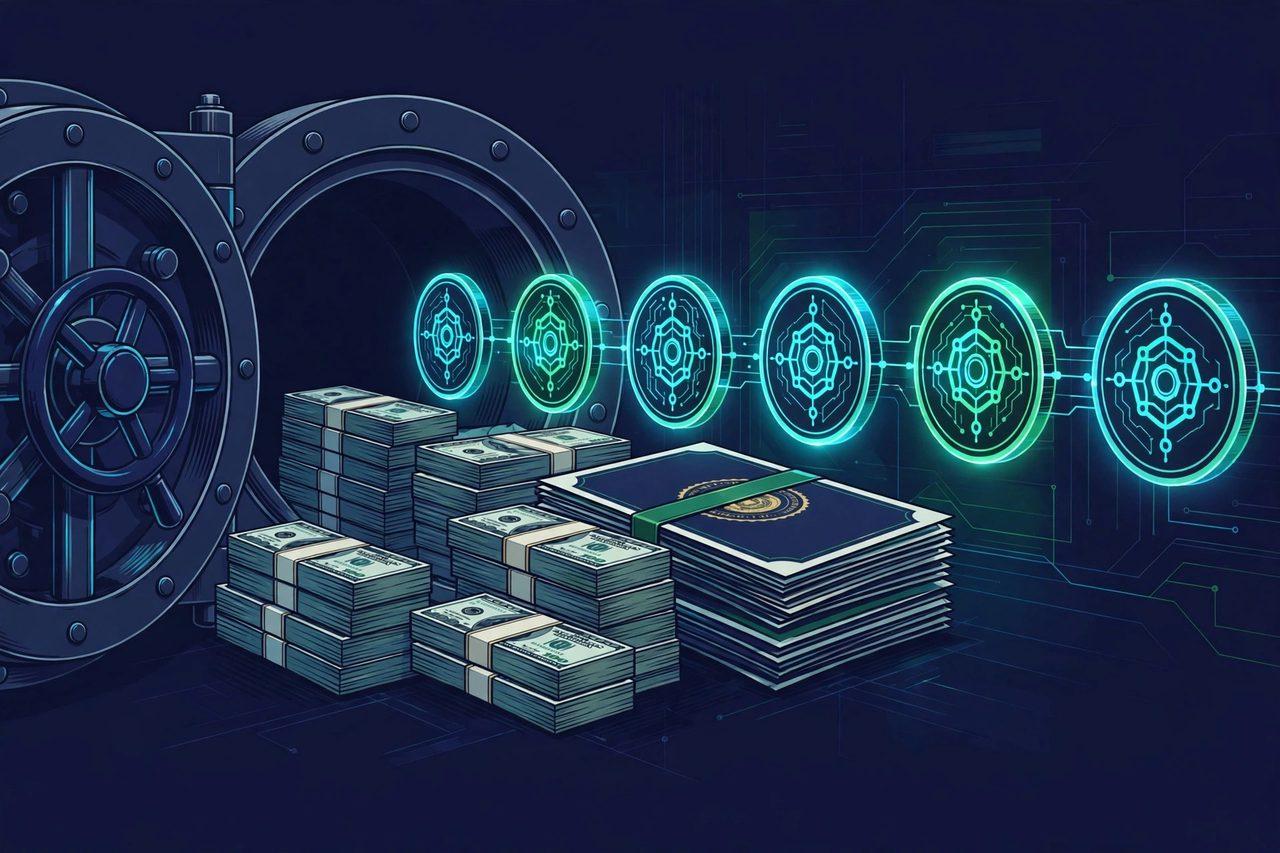
1. Fiat-backed: one token, one dollar of reserves
The simplest model is fiat-backed. The issuer holds dollars — cash, bank deposits, short-term Treasury bills and similar liquid assets — and mints one token for every dollar held. USDT and USDC both work this way, and both publish attestations from independent accounting firms listing the cash, Treasury bills and short-duration repos behind each token. The peg holds because of redemption: an authorised participant can hand back one token and receive one dollar, or deposit one dollar and mint one token. When the token trades at $0.999, arbitrageurs buy it cheap and redeem at par; when it trades at $1.001, they mint and sell. That loop is the peg's real engine — not the issuer's promise, but the profit in enforcing it. The trade-offs are centralisation and counterparty risk: the issuer can freeze addresses, faces regulatory action, and depends on its banks. USDC briefly fell to about $0.87–0.88 in March 2023 when Circle disclosed reserves held at the failed Silicon Valley Bank — a reminder that even the most transparent fiat-backed token can wobble when a reserve bank fails. The US GENIUS Act now requires US-permitted issuers to redeem at par within two business days, which hardens that redemption promise into law.
2. Crypto-backed: over-collateralization absorbs the volatility
The second model replaces bank reserves with on-chain collateral. DAI, issued by the MakerDAO protocol, is the canonical example. To mint $100 of DAI, a user must lock significantly more than $100 of ETH or another approved asset — typically 150% or more, so at least $150 of collateral for every $100 minted. That over-collateralization buffer is what absorbs a falling ETH price before DAI itself loses backing. If collateral drops below the liquidation threshold, smart contracts automatically sell it to repay the debt, plus a penalty. MakerDAO also runs a Peg Stability Module that lets users swap USDC for DAI at a 1:1 ratio with no slippage, capping small deviations. The worked example makes the safety margin concrete: lock $1,500 of ETH, mint $1,000 of DAI, and ETH can fall 20% — your collateral drops to $1,200 — without the position becoming undercollateralized. The risks here are different from fiat-backed tokens: smart-contract bugs, oracle manipulation, and liquidation cascades in a flash crash, when prices gap down faster than liquidators can respond.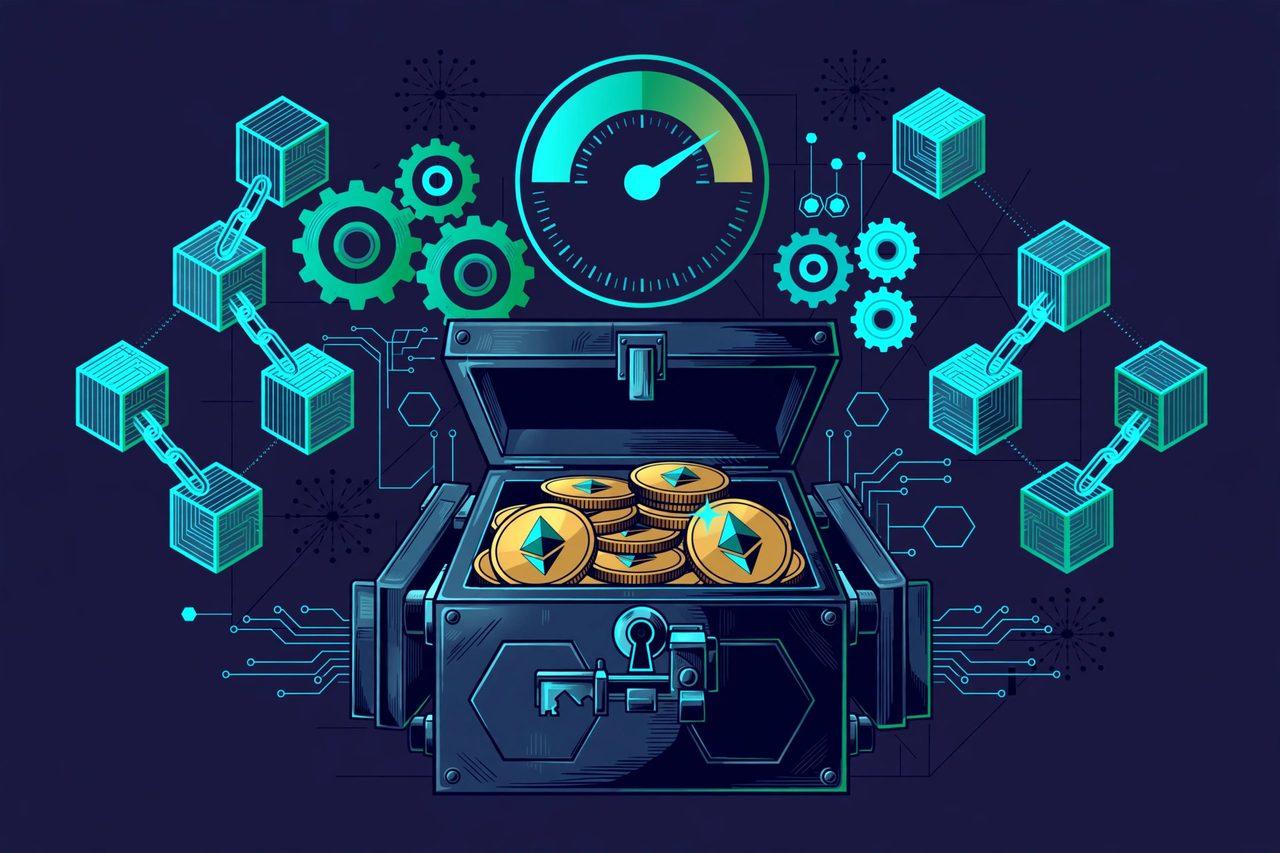
3. Algorithmic: the model that failed in public
The third model, algorithmic stablecoins, tried to hold the peg with no hard reserves at all, using a two-token arbitrage loop that minted and burned a sister token against the stablecoin. Terra's UST is the worked example of what happens when that loop turns reflexive: when UST slipped slightly in May 2022, the redemption mechanics required minting ever more LUNA, which crashed LUNA's price, which destroyed confidence in UST, which accelerated redemptions — a death spiral that wiped out the peg entirely. DAI, by contrast, held its peg through the same crisis with only minor deviations, which is why overcollateralized designs are now treated as far more resilient than algorithmic ones. The lesson for readers is blunt: if a stablecoin's peg depends on the rising price of its own sister token, it is not backed — it is leveraged.
4. A beginner's checklist before holding any stablecoin
- What backs it? Fiat reserves, crypto collateral, or an algorithm — and how much? One-to-one fiat, 150%+ crypto, or nothing hard at all are very different answers.
- Can you redeem it, and how fast? Par redemption within days is the peg's anchor; slow, gated or permissioned redemption is a warning sign.
- Who attests the reserves, and how often? Monthly attestations from a named accounting firm beat a marketing page every time.
- Has it depegged before, and why? A brief, explained depeg with reserves intact (USDC, March 2023) is a different story from a structural collapse (UST, May 2022).
- What is it actually for? Trading, DeFi collateral, payments and savings have different risk tolerances — a token fine for a ten-minute trade may not be the one to hold for a year.
FAQ
What are stablecoins the same as dollars? No. USDT is a token backed by reserves intended to match its circulating supply; it trades close to $1 but is not legal tender and carries issuer counterparty risk.
Why does USDT sometimes trade at $0.999 instead of exactly $1? Small deviations are normal market noise; arbitrageurs profit by buying below $1 and redeeming at par, which pushes the price back.
Is DAI safer than USDT? They carry different risks, not a single ranking: DAI avoids bank and issuer risk but adds smart-contract and liquidation risk; USDT avoids those but depends on its issuer's reserves and banks.
What happened to Terra's UST? It lost its peg in May 2022 when its algorithmic mint-and-burn loop turned into a death spiral with its sister token LUNA.
Can a stablecoin pay interest? Some products offer yield on stablecoin deposits, but the yield comes from lending or protocol rewards, not from the peg itself — and the GENIUS Act's yield rules have pushed some of that activity on-chain. Always separate the token's stability from the product's yield risk.
For the wider DeFi picture, our TVL guide is here: https://zimbuck.com/blogs/889/What-Is-TVL-in-DeFi-How-Total-Value-Locked-Works — and the Zimbuck News page is here: https://zimbuck.com/pages/zimbucknews with discussion at https://zimbuck.com/groups/zimbuckmarketnews . A clear explainer of the three peg mechanisms is here: https://eco.com/support/en/articles/11506305-what-is-a-stablecoin-usdc-usdt-dai-and-how-they-work-in-2026 . This is market news and general information only, not financial advice. Join Zimbuck at https://zimbuck.com to follow more crypto learning guides.




